

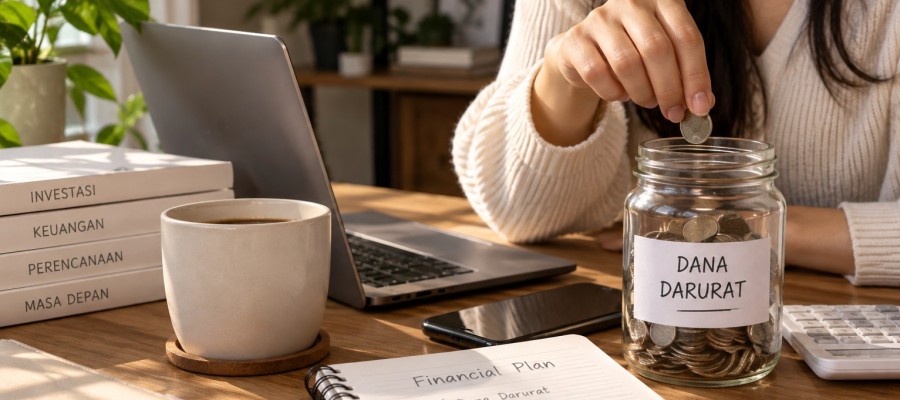


Amidst the ambition to increase income and chase lucrative investment returns, many people often overlook one of the most crucial pillars of personal finance: an emergency fund. Yet, without this foundation, all future plans and years of accumulated savings can collapse in an instant when an unexpected financial crisis strikes.
Why Is an Emergency Fund the Primary Financial 'Buffer'?
Life often brings unpleasant surprises—from sudden job loss and emergency medical expenses to urgent home repairs. Without a reserve fund, these unforeseen costs may force you to drain savings intended for education or vacations, sell off assets or investments prematurely (potentially at a loss), or fall into the trap of long-term consumer debt.
Simple Ways to Start Building an Emergency Fund (No Need to Wait for a Large Salary!)
Begin by listing your essential monthly costs, such as food, housing (rent or mortgage payments), transportation, utility bills, and debt obligations.
Tailor the size of your emergency fund to your personal circumstances, the number of dependents you have, and the stability of your employment.
Set aside a portion of your income as soon as you receive your paycheck—no matter how small the amount. Consistency is far more important than the initial sum.
Do not mix your emergency fund with your daily operating account; otherwise, it might easily be spent on impulsive purchases.
Remember, the purpose of an emergency fund is security and easy access—not the pursuit of high returns. Keep your funds in low-risk instruments that can be liquidated at any time if an urgent need arises.
Source: jago.com
<< Back